August 15, 2023
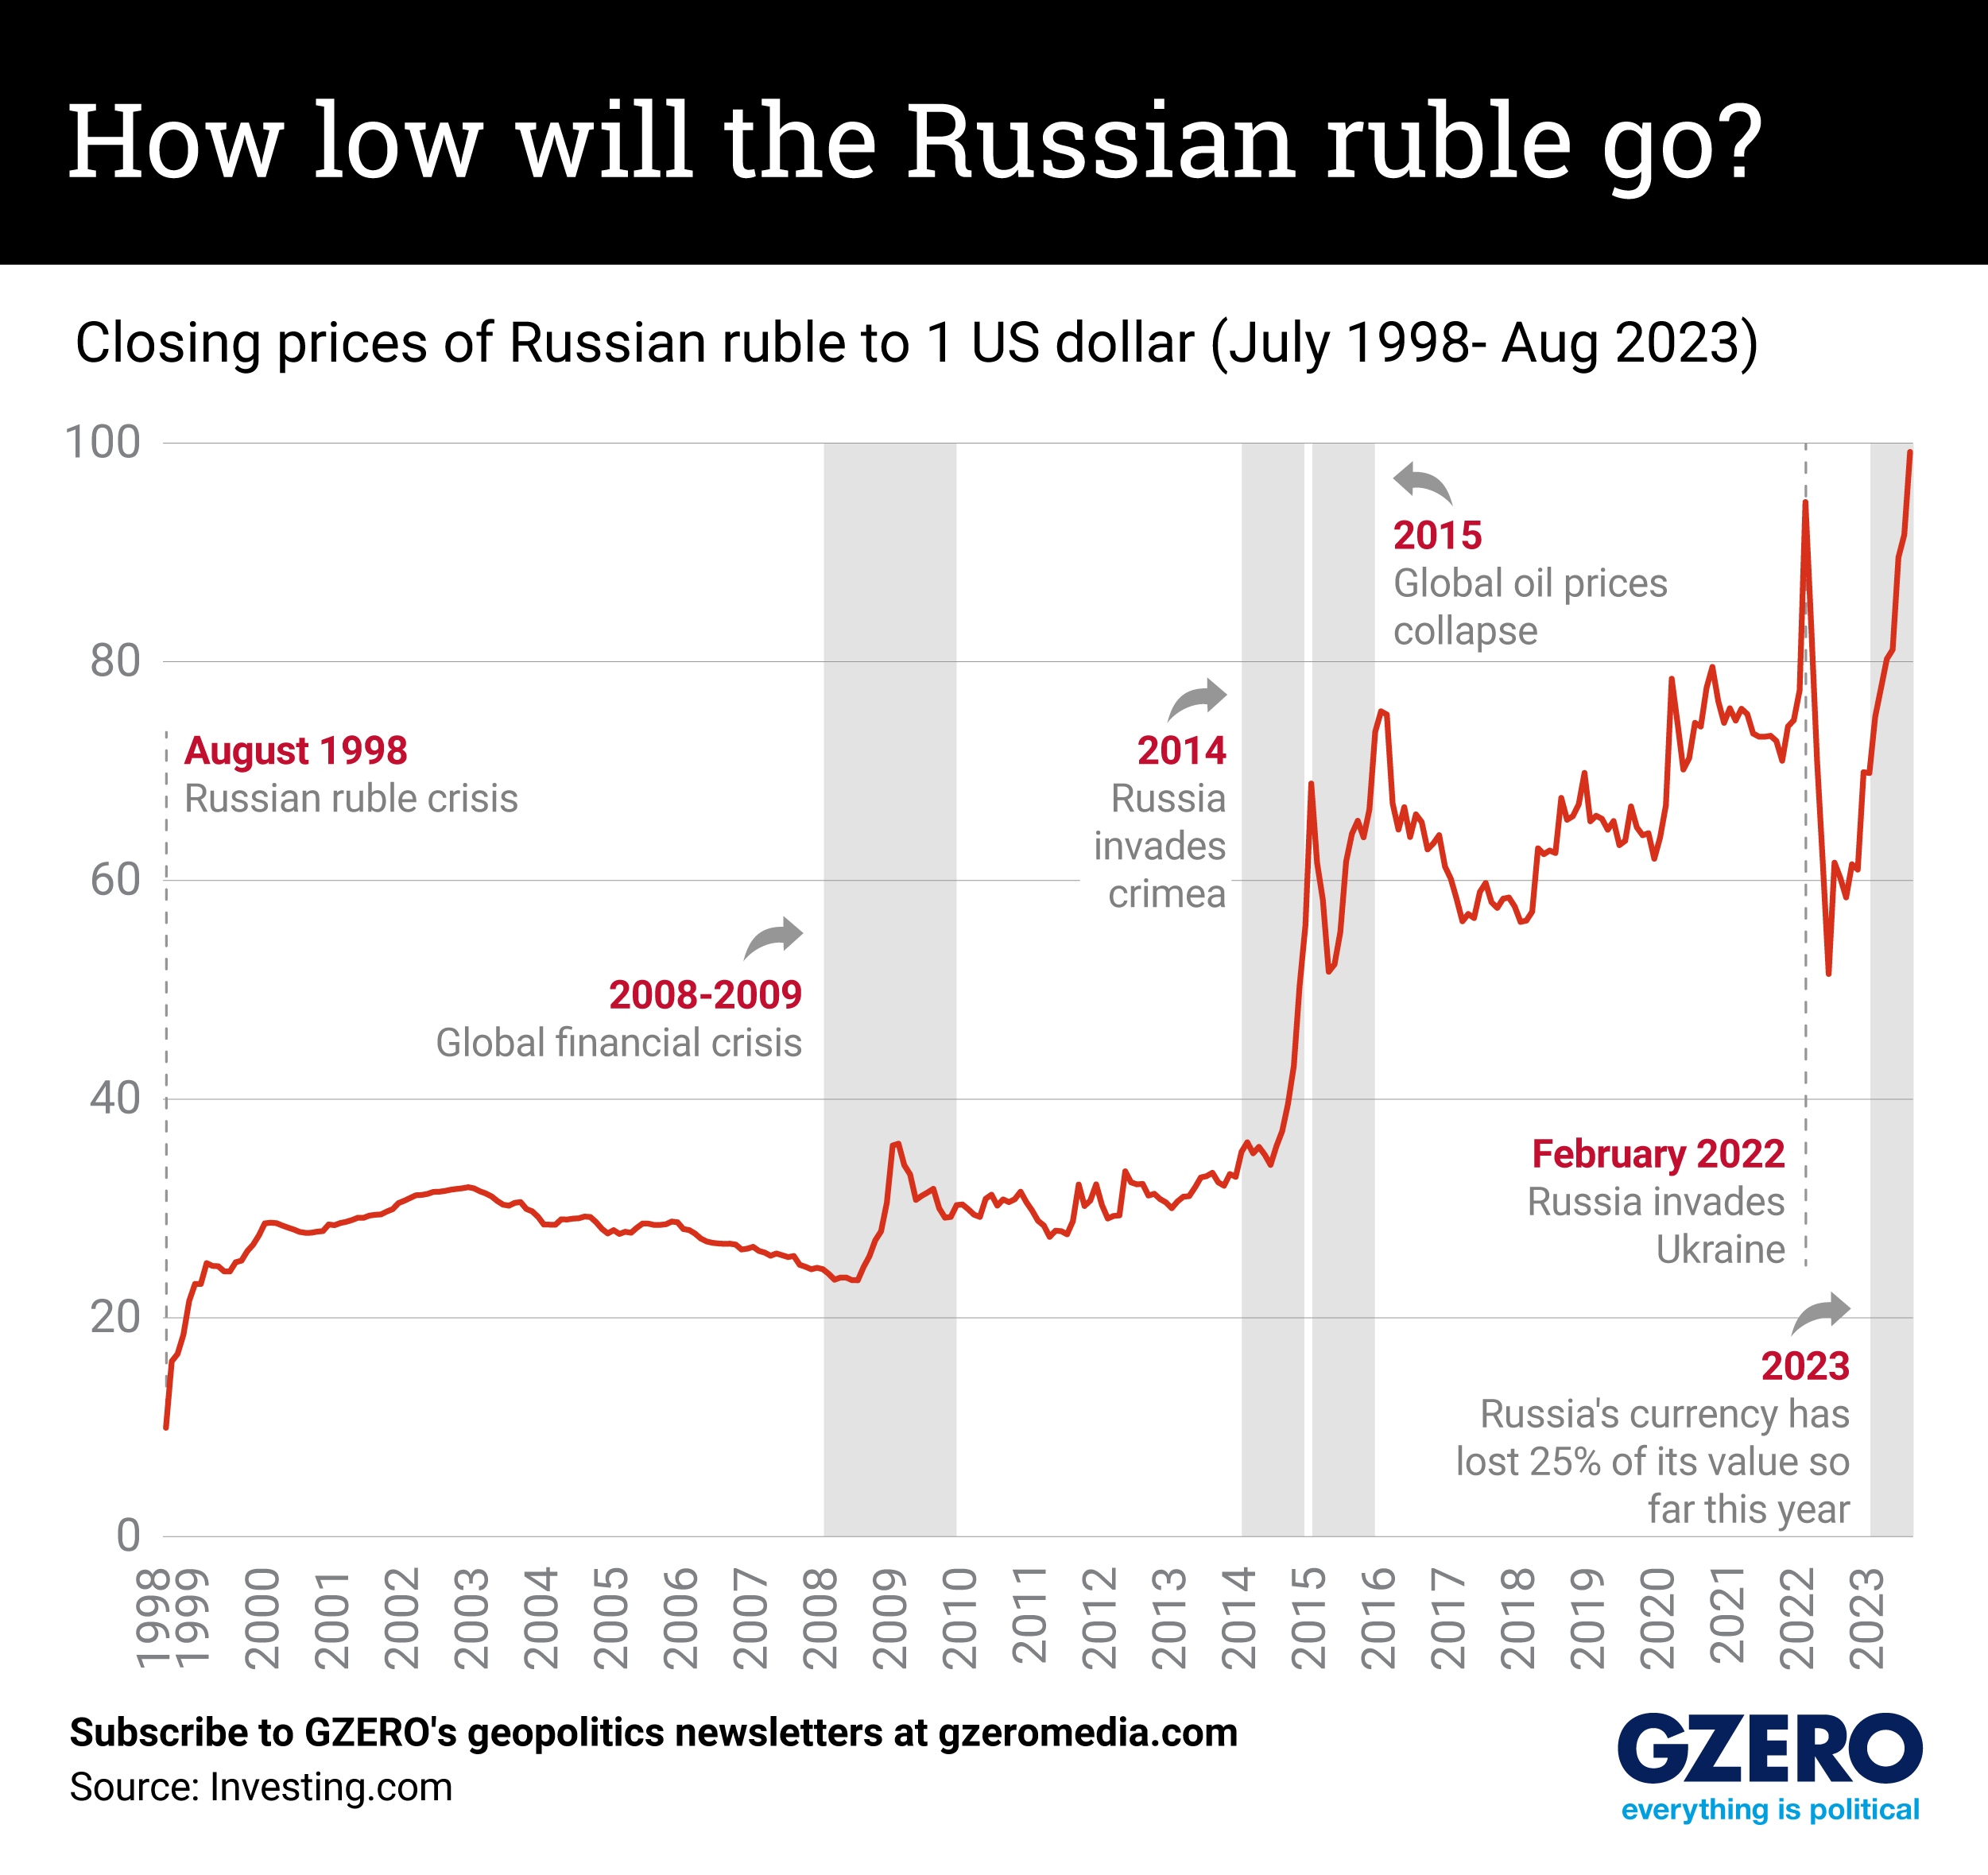
In an emergency meeting on Tuesday, Russia’s central bank raised interest rates to 12% (up from 8.5%) after its currency reached an almost 17-month low against the US dollar. Clearly the Kremlin is spooked that the Russian ruble has lost 25% of its worth against the greenback over the past seven months alone.
The ruble – which this week slid past 101 against the US dollar, before recovering slightly to 98 on Tuesday – has ebbed and flowed since Russian forces invaded Ukraine in Feb. 2022. For context, when oil prices were soaring last July (bolstered by the Kremlin's capital controls), the ruble touched around 61 to the dollar. But many analysts are skeptical that this move will be able to stabilize the ruble, warning that Western sanctions will make it very difficult for Moscow to attract foreign investment.
Still, last summer, things looked pretty rosy for the Russian economy due to high oil and gas prices which, many suggested, were scarcely being impacted by harsh Western sanctions.
At the time, Russia’s trade surplus was further bolstered by the fact that imports fell as Russians’ spending habits were crimped by the uncertainty of war.
But the current currency turndown shows that when compounded by a range of other fiscal and economic factors, Western sanctions are in fact having a strong impact on Moscow’s trade balance – and the value of its currency.
The decline is significant enough that the Bank of Russia last week announced that it would stop buying foreign currency for the remainder of the year in a bid to avoid further volatility.
So what are the key factors at play?
Energy revenue is down. Western sanctions, augmented by a cap on oil prices introduced by G7 countries in recent months, are hurting the Kremlin’s bottom line. Cash inflows from oil and gas, Russia’s main exports, have fallen by 47% in the first six months of this year compared to the same period in 2022. Although countries like China and India continue to buy large amounts of Russian oil and gas, much of this has been gobbled up at a steep discount.
At the same time, imports have recovered in part because the state itself relies on things from abroad to keep its war machine pumping. And its military spending is only growing. Consider that Russia has doubled its 2023 defense spending target from the previous year to more than $100 billion a year.
Capital flight. Making matters worse, this dynamic has been exacerbated by the fact that many Russians have been pulling their assets from the Russian banking system amid fears about regime instability. According to the central bank, Russians withdrew a whopping 100 billion rubles (around $1 billion) from the banking system over just a few days amid Wagner chief Yevgeny Prigozhin’s short-lived mutiny back in June.
Recent events have led to increased calls to make borrowing costs higher, culminating in today's emergency measures. Indeed, Putin’s top economic advisor said earlier this week that loose monetary policy is to blame for the ruble’s downward spiral. Though the bank raised interest rates to 8.5% last month, it was the first steep hike in more than a year.
Looking ahead. While a weak ruble could actually help the Kremlin fund its war effort – more foreign currency would translate into more rubles to buy stuff – brewing chatter about current parallels to Russia’s last deep financial crisis, 25 years ago on Aug. 17, do not look good for a regime trying to project competence and strength. So how do current trends compare to Russia’s last financial catastrophe of 1998? We take a look at the ruble’s value against the US dollar since then.
More For You
Venezuelan opposition leader Maria Corina Machado holds a Venezuela flag while greeting supporters as she arrives in Caracas after travelling by road from Barquisimeto, where she made her first public appearance following her return to the country after nearly a year abroad, in Caracas, Venezuela, October 25, 2026.
REUTERS/Leonardo Fernandez Viloria
Ian Bremmer analyzes what the return of Venezuela's opposition leader will mean for its democracy.
Most Popular
Representatives of secondary school pupils organisations Les Lyceens vice-president Louis Letoublon (3rd L), Renouveau Lycee president Nathanael Combary (2nd R), Renouveau Lycee Monica-Shannon Ongmilan (L), and Bordeaux Academy representative to the National Council for High School Life Elliot Hostin (R), speak to the press as they leave the Hotel Matignon after a meeting with French Prime Minister on October 26, 2026
Paoloni Jeremy/ABACA via Reuters Connect
After weeks of student-led protests over poor conditions in French schools, the government has promised to replace its controversial university admissions platform by 2028.
- YouTube
In this Quick Take, Ian Bremmer breaks down Brazilian President Luiz Inácio Lula da Silva’s historic re-election victory and what it means for the country’s political future and democracy.
Brazil’s leftwing President Luiz Inácio Lula da Silva of Brazil staged an astonishing comeback on Sunday to win a record fourth term, breaking a string of recent right-wing victories in Latin America.
© 2025 GZERO Media. All Rights Reserved | A Eurasia Group media company.